Tesla Trades at 331 Times Trailing Earnings While Facing Growing Competition From China's BYD. Is Elon Musk's Premium Valuation Still Justified?
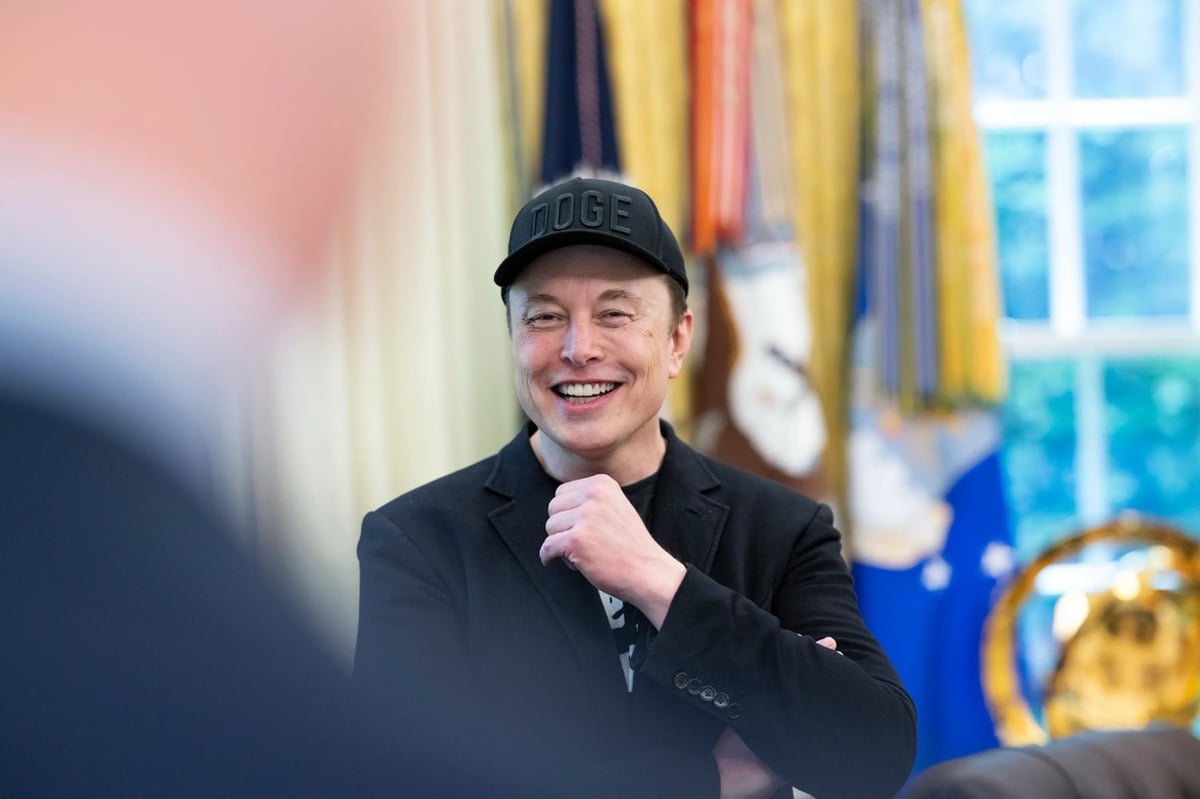
Does Tesla stock still deserve to be valued at a premium derived from CEO Elon Musk's leadership?
Overview
Tesla (NASDAQ: TSLA) is a battleground stock, and its highly growth-dependent valuation creates a solid foundation for the bear case. As of this writing, the stock is trading at approximately 331 times its earnings over the trailing-12-month period. That's a lofty valuation for a company that's currently facing some significant business headwinds.
While revenue increased 26% year over year in the second quarter, Tesla's net income fell 5% to $1.1 billion. Tesla did see substantial demand improvement in Q2, but this was partially achieved by cost-cutting moves that drove margins lower.
Details
In addition to competitive pressures from other automakers, CEO Elon Musk's electric vehicle (EV) company faces a particularly significant threat from the rise of the Chinese EV maker BYD. With Tesla's earnings under pressure, does it still make sense to pay a substantial premium for Tesla stock?
Source
Originally published at www.fool.com.