One Wall Street Analyst Just Said Tesla Stock Could Be Worth $840: Time to Buy?
The analyst update is not particularly significant on its own, but it helps highlight a Tesla business that deserves more attention.
Overview
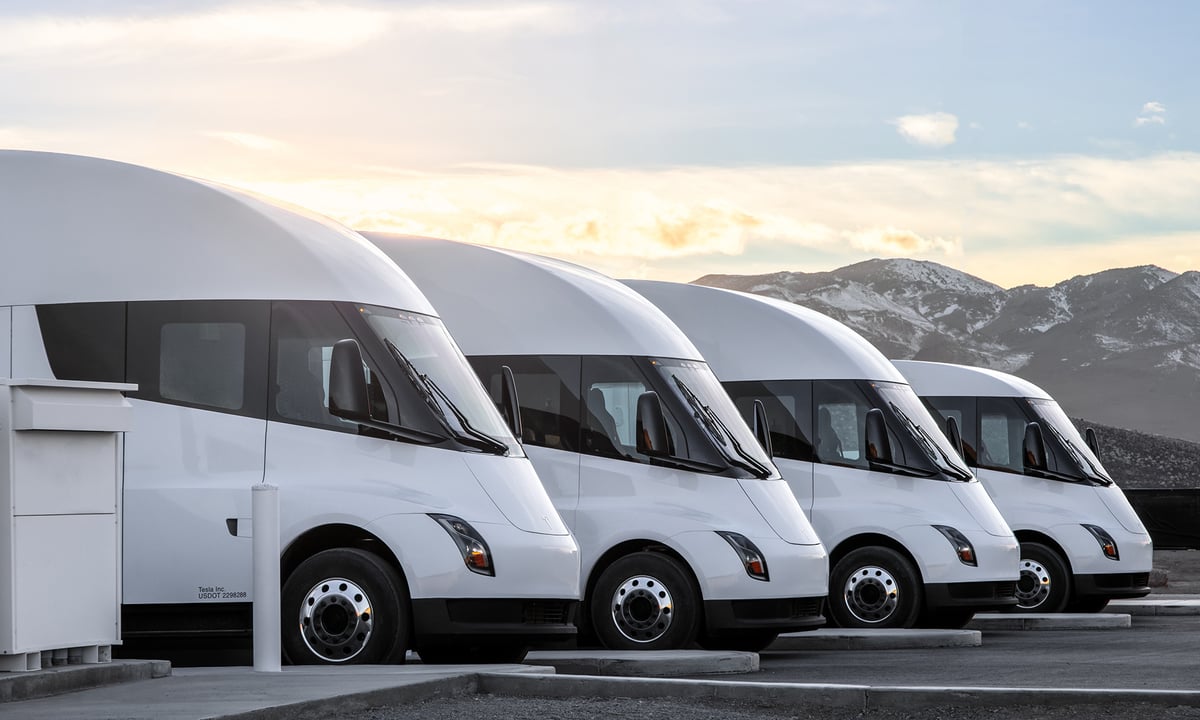
A Morgan Stanley analyst, Andrew Percoco, recently raised his bull-case target price for Tesla (NASDAQ: TSLA) from $820 to $840 while maintaining an equal-weight rating and a $400 price target in his base-case scenario. (The shares now trade for about $357.) Wall Street analysts often provide a range of price targets reflecting various outcomes, and investors shouldn't get too excited by one that nudges the target higher by 2.4% in the best-case scenario. Nevertheless, one reason for the update highlights the long-term potential of a part of Tesla that doesn't get enough attention.
Although the company is best known for its hardware products, including electric vehicles (EVs) and energy storage, its future lies in higher-margin recurring revenue from its physical solutions, namely robotaxis (including its dedicated robotaxi, Cybercab) and Optimus robots. To be clear, if you don't believe in these businesses, then you have no other reason to hold a stock trading at 200 times its estimated 2026 earnings.
Details
However, Tesla's investment case is exciting and, on the transportation-as-a-service side, rests on the potential for recurring fare revenue from its own Cybercabs, its share of fare revenue from third-party operators, and full self-driving (FSD) software. Optimus will likely operate under a robot-as-a-service model, generating long-term recurring software revenue.
Source
Originally published at www.fool.com.